Subscribe
The Inside Deutsche Bank leak was obtained by Indian author and journalist, Josy Joseph, and South African investigative journalist, Khadija Sharife. The investigation was coordinated by Barracuda Media in South Africa, with technical support from the Data and Research Center (DARC) in Germany.
In August 2026, Democratic Senator Ron Wyden, a senior member of the U.S. Senate Finance Committee, published a damning report called Looking the Other Way, which railed against the financial institutions whose failures had enabled Jeffrey Epstein to operate.
Describing Deutsche Bank's relationship with Epstein, he told CNN: “For Deutsche Bank to be involved in the whitewashing business is absurd. They failed to promptly report to the Treasury more than $250 million in suspicious transactions that were tied to Epstein.”
“That is brand new information for the public,” Wyden said, as his extensive report recommended a criminal investigation into Epstein’s bankers.
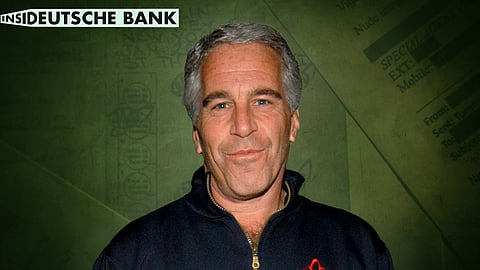
Now a new set of leaked documents from inside Deutsche Bank reveal the payments are actually much bigger than even Wyden knew. And that he was onboarded by the bank after he was involved in the sexual exploitation of a minor and another bank disassociated themselves with him.
An internal document from Deutsche Bank’s U.S. Financial Crimes Intelligence Unit shows that the bank filed 21 suspicious activity reports, or SARs, involving 3,000 transactions between October 2013 and May 2019 relating to Epstein or his companies. In total, these transactions amounted to $581.9 million.
In banking, a SAR is a confidential document filed with authorities when a bank identifies transactions or activities it suspects may involve financial crimes.
The internal document is part of 15+ million files leaked by two whistleblowers to Indian author and journalist, Josy Joseph, and South African investigative journalist, Khadija Sharife. The whistleblowers, whose identities are being protected, copied the files and removed them from Deutsche Bank.
The Inside Deutsche Bank files also revive the story of how the bank onboarded and kept a convicted sex offender that had previously been offboarded by JP Morgan Chase. They also show the behind-the-scenes as machinations as the bank grappled with a crisis of its own making.
By the time Deutsche Bank accepted him as a client in August, 2013, Epstein's crimes involving the sexual exploitation of a minor were a matter of public record.
Despite this, internal documents show the banking of Epstein at Deutsche Bank involved sign-off at the highest levels, including by the head of anti-financial crime and compliance, and the then-general counsel for Deutsche Bank America.
Documents show the bank maintained its relations with the “high-risk” Epstein from August, 2013 until informing him of his offboarding in late 2018, a process that would take a further six months.
According to Wyden’s report, Deutsche Bank only retroactively filed SARs concerning Epstein after his July 2019 arrest on federal charges of sex trafficking of minors and conspiracy to commit sex trafficking of minors.
In the leaked Deutsche Bank files, reporters discovered a report produced in 2020 by independent monitors. The monitors were tasked with tracking whether Deutsche Bank was complying with legal consent orders — including one on Epstein.
In the document the monitors outline various red flags about Epstein that the bank knew about before taking him on board, such as “widely-known interactions with the legal system including a guilty plea and sentence for two prostitution crimes.”
Recounting how Epstein was first onboarded, the monitors wrote that, “Senior leaders in the WM (Wealth Management) Americas group were well aware of these issues at the time, but approved the relationship via email.”
In a response, the bank said: “Deutsche Bank notified Jeffrey Epstein in December 2018 that the Bank intended to close his accounts. The Bank worked to ensure that Epstein’s assets were transferred out of the Bank in the following months.”
The bank said it “acknowledges its error of onboarding Epstein in 2013 and regrets our historical connection with him. We have cooperated with regulatory and law enforcement agencies and the U.S. Congress regarding their investigations and have been transparent in addressing these matters in parallel.”
“In recent years Deutsche Bank has made considerable investments in strengthening controls, including bolstering our anti-financial crime processes through technology, training and additional staff with dedicated expertise.”
In mid-2013, a former banker at JPMorgan Chase who had moved to Deutsche Bank rekindled a relationship with an ex-client whose name was already synonymous with predatory abuse: Jeffrey Epstein.
That year, JPMorgan Chase was winding down its banking relationship with Epstein; his 2008 guilty plea to prostitution-related charges involving a minor and his subsequent registration as a sex offender had made him a liability.
JPMorgan Chase did not respond to a request for comment.
But Deutsche Bank viewed Epstein as a financial whale, classifying him internally as an ultra-high-net-worth individual. A “know your customer” form for Epstein revealed an estimated net worth of between $100 million and $500 million.
Documents show that in August 2013, he began transferring his company accounts to Deutsche Bank. That month, the bank opened a corporate account for Southern Financial, one of his companies, based in the U.S. Virgin Islands. A document related to this lists his annual income from Southern Financial at about $10 million.
Ghislaine Maxwell, Epstein's former partner and associate who is now imprisoned in the U.S., was a beneficiary of one of Epstein’s trusts.
In a 2015 email the bank described her as an alleged “co-conspirator in Epstein’s illegal activities,” but allowed the arrangement to go ahead, concluding that because she was not a Deutsche Bank client, but only a beneficiary of the trust, they would allow it. The same email, titled “cleared,” saw an alert concerning Maxwell and the trust given a pass. The trust was given the all-clear from “a reputational and (anti-money-laundering) risk perspective.”
During Epstein's relationship with Deutsche Bank, his accounts were used to make numerous payments to people who had been publicly identified as alleged co-conspirators in his abuses. The bank failed to adequately investigate or block these transactions, according to its records and financial regulators."
The monitoring report from 2020 shows that Deutsche Bank would “continuously” expand” Epstein’s relationship with the bank “without appropriate documentation from the relevant controls.” Ultimately, according to New York regulators, Epstein, his entities, and his associates would open more than 40 accounts with the bank.
In November 2018, Epstein was thrust back into the public spotlight by the Miami Herald's landmark investigative series, Perversion of Justice, by journalist Julie K. Brown.
Brown exposed how Epstein had secured an extraordinary deal with federal prosecutors in 2007, allowing him to avoid federal sex-trafficking charges, leaving victims unaware of his sweetheart deal and receiving a lenient sentence in Florida.
Crucially, the investigation gave a voice to survivors who had been silenced for years, with Brown tracking down dozens of victims and persuading several to speak publicly.
In December 2018 Deutsche Bank informed Epstein that he would be offboarded.
By 2019, the scrutiny triggered by Brown’s story led to renewed law enforcement efforts, culminating in Epstein’s arrest on sex-trafficking charges in July of that year.
In a March 2020 email titled “confidential,” which was copied to Deutsche Bank senior executives, it was stated that a Deutsche Bank staffer had sent foreign banks two letters of recommendation for Epstein’s investment companies in the spring of 2019, while his offboarding was in progress.
According to the email, the second letter had made “a specific representation that the relevant account had not experienced anti-money laundering problems.” The email went on to admit that the bank did not, by then, have a policy in place for writing “these types” of reference letters for clients.
Brown’s story triggered an awakening within Deutsche Bank. By August 2019, it appears that two investigations into Epstein were underway, including one in the U.K.
In September 2019, a summary from the internal U.K. investigation found at least, “112 high risk transactions,” including payments from Epstein’s corporate accounts. The investigation identified transactions that could potentially have been related to sexual abuse, the summary shows. In an email the same month, multiple companies were identified for potentially enabling the abuse of minors, including at the infamous Zorro Ranch in Stanley, New Mexico. The investigation also identified a “shadowy” charitable organisation named Gratitude America Ltd, through which Epstein possibly laundered his money.
Three days after Epstein’s July, 2019 arrest, Deutsche Bank finally concluded its drawn out process of de-banking him, shutting down his two remaining accounts.
In July 2020, Deutsche Bank CEO Christian Sewing told colleagues that onboarding Epstein was a critical mistake and should never have happened.
U.S. court filings show Deutsche Bank had hoped to create $2 million to $4 million in revenue per year from the business relationship.
But even in a best case scenario, these figures would be dwarfed by the bank’s eventual Epstein-related fines. In 2020, Deutsche Bank was ordered to pay $150 million to New York’s Department of Financial Services in connection to failures in dealing with Epstein, among other matters, and in 2023 it agreed to pay $75 million to settle a class action lawsuit by victims who had alleged that Deutsche Bank knowingly benefited from and facilitated Epstein's abuses.
Deutsche Bank’s high-stakes gamble with the financier never paid off, and he would die by suicide in prison on August 10, 2019.
Follow TNM's WhatsApp channel for news updates and story links.
